
Types of Wills in India: Know the differences
Estate Planning
Aug 25, 2024
Plan Your Retirement with Our Qualified Financial Advisors
Your first financial plan is free
Key takeaways
Receiving money from a parent, sibling, friend or another family member may feel like a straightforward transfer, especially when it is meant to support a home purchase, meet a financial need or simply pass on family wealth. But a large transfer can have different tax implications depending on who gives it and why you receive it.
Under the Income Tax Act 2025, certain gifts are taxable as income, while others are specifically excluded from the gift-tax provisions. The rules around gift tax in India therefore depend on the relationship between the giver and recipient, the nature of the asset transferred and the circumstances of the transfer.
A ₹20 lakh gift from a parent, for instance, doesn’t follow the same tax treatment as ₹20 lakh received from a friend. Similarly, money received as a wedding gift or property received through inheritance is considered under separate provisions. Understanding these distinctions is the starting point for determining whether a gift is taxable or exempt.
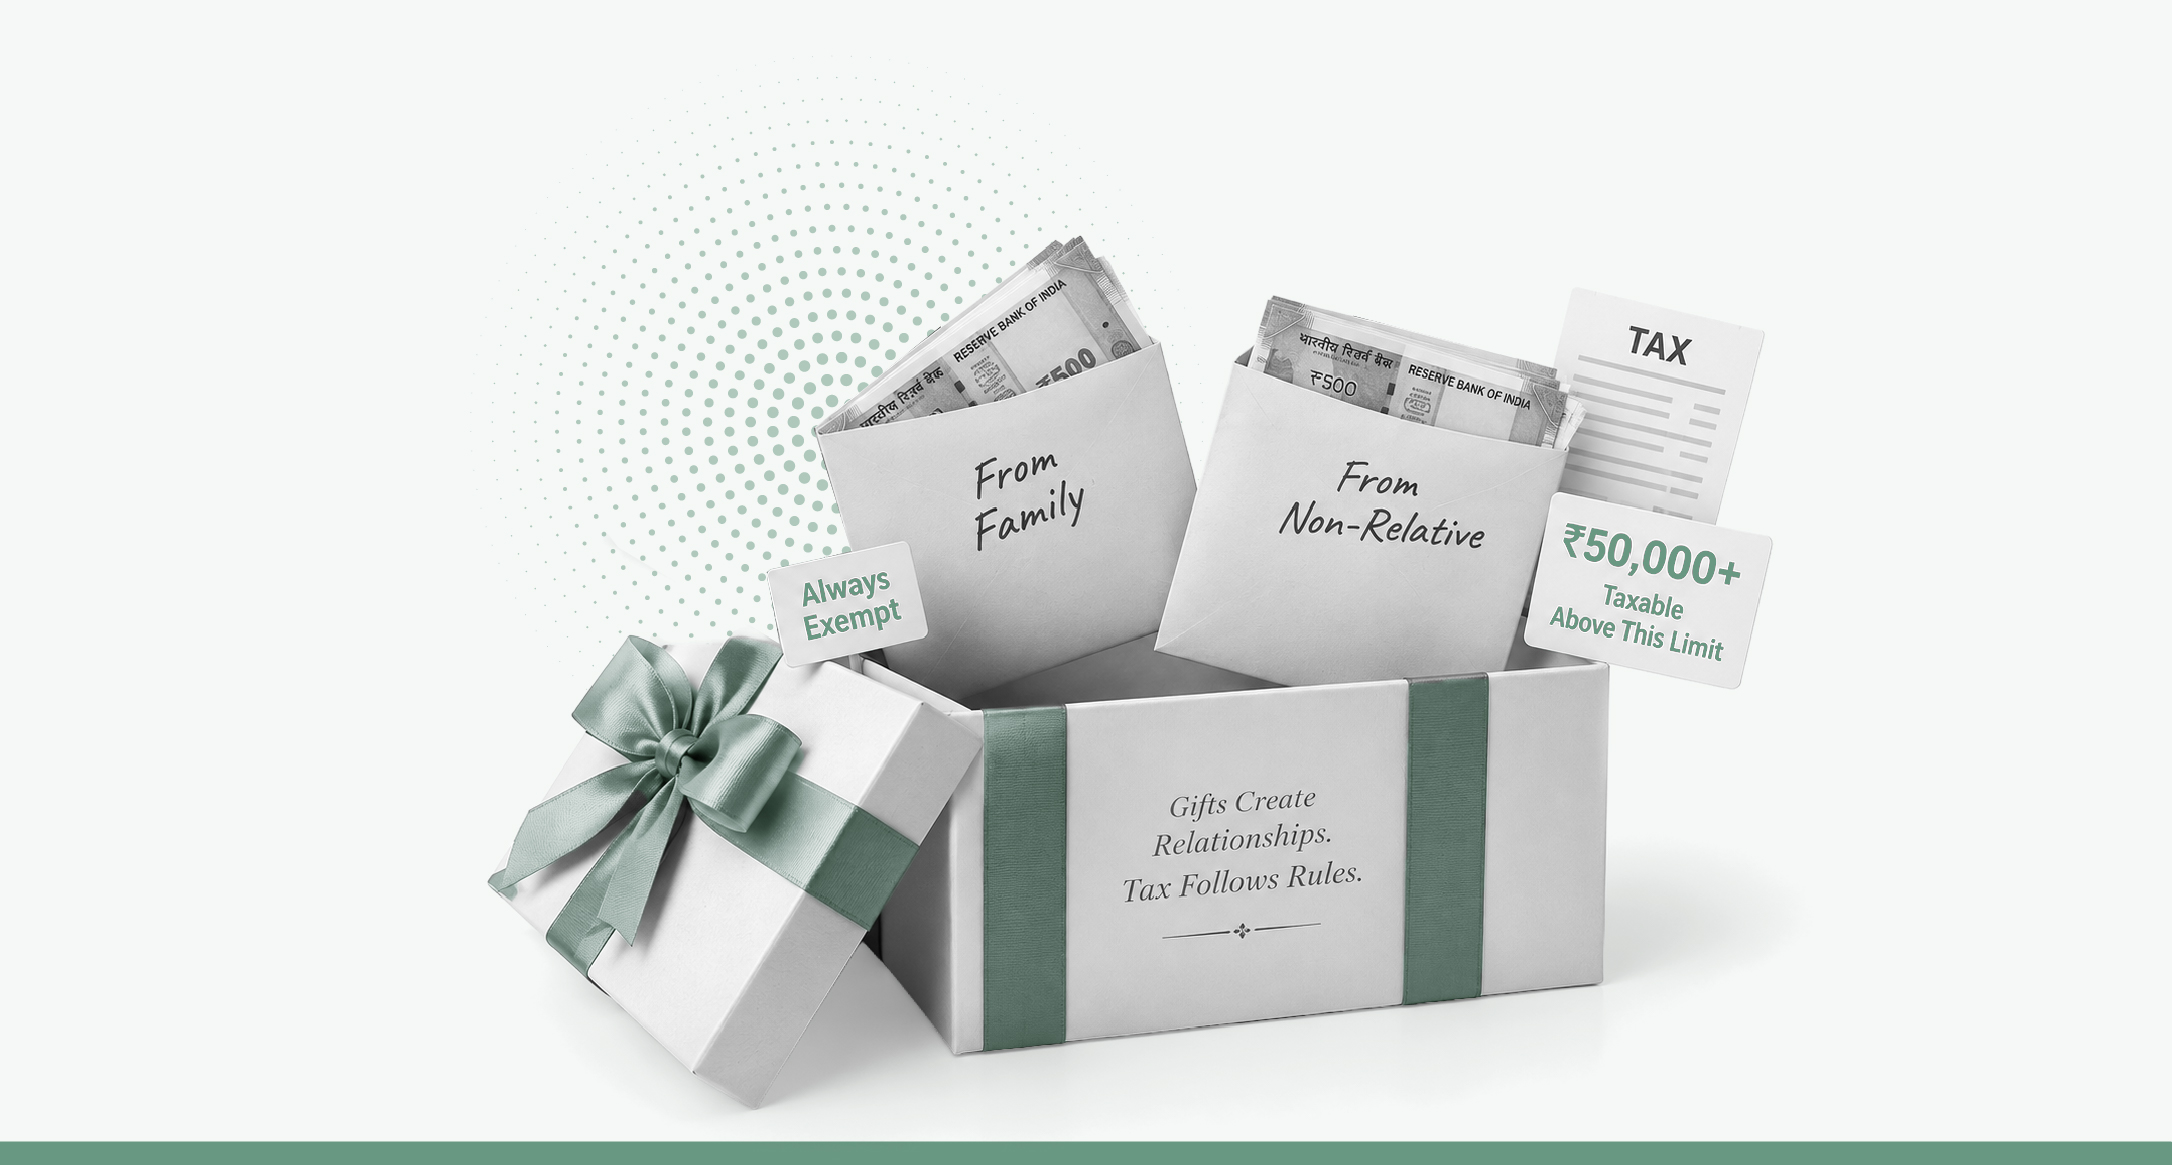
Anyone on the law’s list of relatives can give you any amount, whether ₹2 lakh or ₹2 crore, and you owe no tax on it. Section 92(5)(g) of the Income-tax Act, 2025 defines the list:
Your parents are lineal ascendants, so your ₹20 lakh is tax-free. Your spouse’s parents appear on the list as well, because it includes the lineal ascendants and descendants of your spouse. Cousins do not appear on it. A cousin’s gift therefore follows the ₹50,000 limit described in the next section.
Also read: A gift deed or a Will? How senior citizens can pass property to their children
Suppose a friend sends you ₹30,000 in April and a former colleague sends ₹35,000 in November. Each amount is below ₹50,000, yet the law adds up everything you receive during the tax year from people outside the relatives list. Your total here is ₹65,000. Since it crosses ₹50,000, the entire ₹65,000 becomes taxable income, including the first ₹50,000. Had the total stopped at ₹50,000, you would have paid nothing.
A gift counts only when it reaches you without consideration, which means you owe no repayment and give nothing in return. Cash, cheque, UPI and bank transfer are all counted alike for this rule. The payment method matters for a separate rule near the end of this guide.
Gifts can also arrive as assets. A friend might hand you jewellery or transfer shares, and a giver outside the list might gift you land. Section 92 covers these too. Movable property such as jewellery, shares, bullion and virtual digital assets is taxable when its fair market value exceeds ₹50,000 and you paid nothing for it. If you paid a part, the taxable amount is the gap between the fair market value and your payment, once that gap exceeds ₹50,000. Immovable property received without consideration is taxable at its stamp duty value when that value exceeds ₹50,000.
The giver decides which rule applies to the very same asset. A flat gifted by your father is exempt, and the same flat gifted by a friend adds its full stamp duty value to your income for the year.
Section 92(3) exempts some gifts on the basis of the occasion or the source. A gift you receive on the occasion of your own marriage is exempt in any amount. If a college friend gives you ₹1 lakh at your wedding, it stays tax-free, while the same ₹1 lakh at a housewarming would be taxable in full. Money or property received under a Will or by inheritance is exempt as well. Gifts from certain registered charitable trusts and institutions also fall outside the charge, subject to conditions.
Also read: India’s birth rate could change how you inherit wealth
A taxable gift has no separate rate. You, the recipient, pay the tax, and the gift is added to your other income and taxed at the slab rates of your regime. For Tax Year 2026-27, the default new regime under Section 202 is nil up to ₹4 lakh and climbs through seven slabs to 30% above ₹24 lakh. A rebate under Section 156, earlier Section 87A, makes the tax nil for a resident individual with taxable income up to ₹12 lakh. The old regime has a smaller rebate of up to ₹12,500 for taxable income up to ₹5 lakh.
The rebate decides what a taxable gift costs you. Take the ₹65,000 from your friend and your former colleague and add it to three different incomes under the new regime.
If your income before the gift is ₹8 lakh, your total becomes ₹8.65 lakh. That sits under the rebate limit, so you pay nothing. If your income is ₹11.5 lakh, your total becomes ₹12.15 lakh and crosses the limit by ₹15,000. Marginal relief then caps your tax at that ₹15,000, plus 4% cess. If your income is ₹25 lakh, the gift lands in the 30% slab and adds ₹19,500 before cess.
The same gift cost nothing, ₹15,000 or ₹19,500, depending on your income. Compare your total tax with and without the gift to see the real cost. 1 Finance Old vs New Tax Regime Calculator can run that comparison for both regimes.
Tax can follow a gift after it is credited to your account, through the income the gift earns. If your parents’ ₹20 lakh goes towards a flat that you rent out, the rent is taxable in your hands. Money from your spouse works differently. Suppose your spouse gifts you ₹5 lakh and you place it in a fixed deposit. The gift is exempt, and the interest is added to your spouse’s income under Section 99 of the 2025 Act (Section 64 of the 1961 Act). Gifts to a minor child are clubbed in the same way.
Selling a gifted asset ties you to the giver once more. Your cost of acquisition is what the previous owner paid, plus any improvements they made, and your holding period includes theirs. Suppose your father bought a flat for ₹40 lakh and gifted it to you, and you later sell it for ₹50 lakh. Your capital gain is measured against ₹40 lakh, the price your father paid. If your father’s and your holding periods together exceed 24 months, the gain is long-term.
Keep the bank or UPI record, and ask the giver for a short signed declaration that states the giver’s name, your relationship, the date, the amount and the purpose. The relationship needs that care, because a giver whose relationship you cannot establish can be treated as a non-relative, and then the ₹50,000 limit applies. For a substantial gift, a gift deed adds stronger support, and immovable property should be registered with stamp duty paid. If the money is meant to be repaid, treat it as a loan and write down the terms. A written loan record keeps it from being mistaken for a gift.
Large gifts should reach you through a bank. Section 269ST of the 1961 Act, now Section 186 of the 2025 Act, bars you from receiving ₹2 lakh or more in cash from one person in a day, in a single transaction or for a single occasion. The penalty equals the cash received and falls on you as the recipient. It applies even when the gift itself is exempt: a ₹2 lakh cash gift from your parents is free of income tax and can still draw a penalty.
Your parents’ ₹20 lakh stayed tax-free because they are on the relatives list. The ₹65,000 from outside the list became income because the year’s total crossed ₹50,000. Before you accept any large transfer, check the giver against the relatives list, add up everything you received from outside it and decide how the money will arrive and be recorded. The tax that follows the gift, on what it earns and on its later sale, deserves the same planning.

The views in the article /blog are personal and that of the author. The idea is to create awareness and not intended to provide any product recommendations.


Plan Your Retirement with Our Qualified Financial Advisors
Your first financial plan is free