
3 best alternative to HDFC Infinia Credit Card (Metal edition)
By Arman Qureshi
Credit cards blogs
Jun 29, 2025
Plan Your Retirement with Our Qualified Financial Advisors
Your first financial plan is free
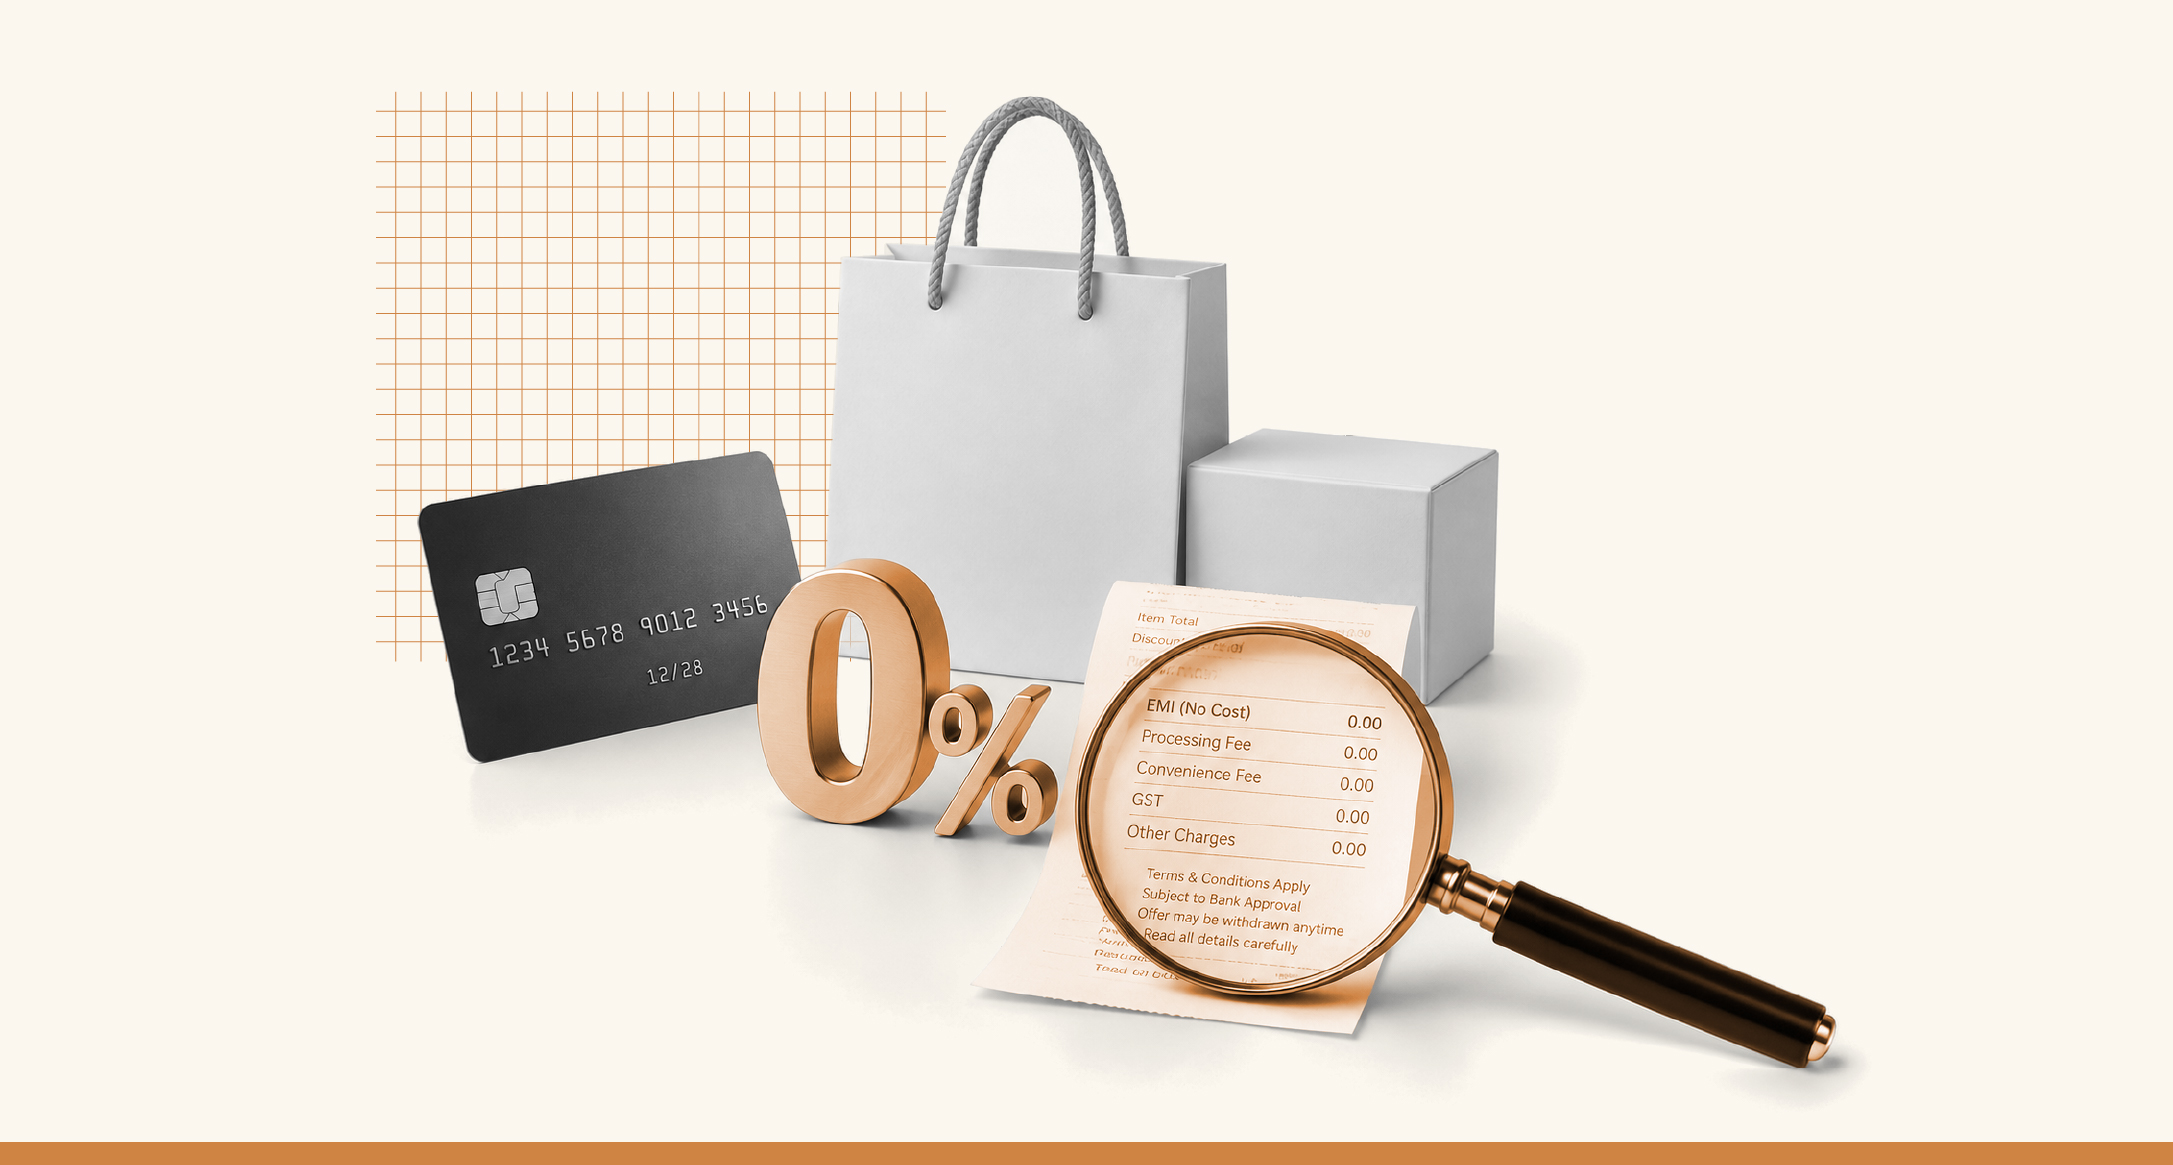
A ₹60,000 phone is available for ₹10,000 a month for six months on zero-cost EMI. Paying the same ₹60,000 over time sounds like an easy choice, but does zero cost mean the credit itself costs you nothing? A zero-cost or no-cost EMI offer usually involves an interest component on the credit card EMI and an upfront discount from the merchant or card issuer designed to offset that interest. Other charges can still affect how much you eventually pay. Before choosing the EMI option at checkout, look beyond the monthly instalment and find out how the offer arrives at its advertised cost.
A regular credit card EMI allows you to spread the cost of a purchase over several months. The card issuer can charge interest for providing that credit. A zero-cost EMI offer is structured differently at the point of purchase. The merchant or card issuer may provide an upfront discount corresponding to the interest charged on the EMI.
RBI’s credit card directions specifically recognise this structure. Card issuers must clearly disclose the principal amount, interest and upfront discount provided by the merchant or card issuer to make the transaction no-cost before converting it into EMI. These details must also appear separately in the credit card statement. RBI also prohibits an EMI carrying an interest component from being presented as zero-interest or no-cost EMI without the required disclosure.
For you, this means the phrase appearing on the checkout page isn’t enough to understand the transaction. The principal, interest, discount and other applicable charges show how the offer actually works.
Consider a simplified purchase of ₹60,000. Suppose the applicable interest over the EMI tenure works out to ₹3,000 and the merchant provides an upfront discount of ₹3,000. The discounted purchase amount becomes ₹57,000, while the interest charged through the EMI brings the aggregate back towards ₹60,000.
The exact EMI schedule depends on the issuer’s interest calculation, tenure and terms. This example only demonstrates how an upfront discount can offset an interest component. You should therefore check whether the discount fully offsets the interest and whether any separate charges remain payable.
Yes, depending on the offer and card issuer. A card issuer may levy a processing fee or another disclosed charge for an EMI conversion according to its applicable terms. Taxes can also apply to relevant fees, charges or interest as prescribed. These amounts need to be included when you assess the transaction.
If a ₹60,000 purchase carries an additional EMI processing fee, the total amount leaving your pocket can exceed ₹60,000 even when the merchant discount offsets the stated EMI interest. The offer page and card issuer’s terms should tell you whether a processing fee applies and how it will be charged.
Check whether you are giving up an upfront discount The cash price and zero-cost EMI price aren’t always economically identical. A merchant may offer one price for an immediate payment and a different promotional structure for an EMI purchase. Card discounts, coupons, instant discounts or other offers may also have separate eligibility conditions.
Suppose a product costs ₹60,000 under the EMI offer but an eligible upfront payment would qualify for a ₹4,000 discount. Choosing the EMI means the relevant comparison may be ₹60,000 against an effective upfront price of ₹56,000, subject to the merchant’s offer terms. That ₹4,000 is part of the financial decision even though it doesn’t appear as EMI interest. Before selecting zero-cost EMI, compare the final amount payable under each payment option available to you for the same purchase.
Start with the total amount payable rather than the size of the monthly instalment. RBI requires transparency when a credit card transaction is converted into EMI. You should be able to identify the principal, applicable interest and upfront discount used to make the offer no-cost. Then check the remaining terms. Look for a processing fee, applicable taxes, the EMI tenure and any conditions attached to the promotional discount.
Also check whether choosing EMI changes your eligibility for another merchant or card offer. A lower price available through another payment method can change the real comparison. Once you have these numbers, compare the total outflow under the EMI option with the amount you would pay using the alternative payment method you would realistically choose.
An EMI divides repayment into monthly instalments, but the underlying purchase still uses your credit facility. How your available credit limit is blocked and subsequently restored depends on the card issuer’s terms and the EMI arrangement. A large purchase can therefore reduce the credit available for other spending even though only one instalment appears in your monthly bill at a time.
Before putting a high-value purchase on EMI, check how much available credit will remain on the card. This becomes particularly relevant if you rely on the same card for regular expenses or planned transactions. RBI requires card issuers to ensure that a sanctioned credit limit isn’t breached without the cardholder’s explicit consent.
Zero-cost EMI doesn’t remove your obligation to pay the credit card bill by its due date. Once an EMI forms part of the billed amount, delayed or incomplete payment can attract charges according to your card issuer’s terms and RBI’s applicable credit card rules.
RBI requires card issuers to disclose their interest rates and methodology for calculating finance charges. Late-payment and related charges can be levied on the outstanding amount after the due date according to the applicable framework. A purchase that began with a promotional EMI structure can therefore become more expensive if repayments aren’t made as required. Consider the EMI alongside your existing card obligations before committing to the tenure.
Returns and cancellations deserve attention because an EMI involves both the merchant transaction and the credit arrangement. The way an EMI is cancelled, reversed or closed can depend on the card issuer, merchant and status of the transaction. Applicable processing charges or other amounts may also be governed by the specific terms of the offer.
If you return an EMI purchase, check whether the merchant refund automatically closes the EMI or whether you need to contact the card issuer. Review the subsequent statement to confirm that the refund and EMI adjustment have been recorded correctly.
RBI’s credit card directions require interest to be levied on the outstanding amount after adjusting for payments, refunds and reversed transactions.
The answer depends on the numbers attached to the particular offer and your finances. Spreading a large expense across several months can help you manage cash flow. The benefit needs to be considered against processing charges, applicable taxes, discounts you may forgo and the effect of the purchase on your available credit.
Affordability also deserves a wider view than the individual EMI amount. A ₹5,000 instalment may fit comfortably into one month’s budget. Several simultaneous EMIs can create a much larger fixed credit card obligation. Check your existing EMIs and card spending before adding another recurring payment.
A zero-cost EMI offer can make a large purchase easier to divide across monthly payments. Its name doesn’t provide enough information to decide whether the transaction is cost-free for you. RBI requires the principal, interest and upfront discount involved in making an EMI no-cost to be disclosed. Use those figures as the starting point. Add any processing charges and applicable taxes, then compare the result with the price available through another payment method.
If the total cost and repayment schedule fit your finances, you can evaluate the offer on those terms. The monthly EMI tells you how the payment is divided. The complete transaction details tell you how much the purchase will actually cost.

The views in the article /blog are personal and that of the author. The idea is to create awareness and not intended to provide any product recommendations.


Plan Your Retirement with Our Qualified Financial Advisors
Your first financial plan is free