


While reviewing your salary structure, you may be given the option to allocate a portion of your compensation towards certain benefits. Should you choose these options, and will doing so actually reduce the tax deducted from your salary? These choices may be offered through a Flexible Benefit Plan (FBP).
But does choosing these benefits actually reduce the tax deducted from your salary? The tax treatment can differ across benefits, with some qualifying for tax exemption subject to prescribed conditions while others may remain taxable. The options available to you depend on your employer’s FBP policy, while the Income Tax Act, 2025 and relevant rules determine how these benefits are taxed.
How does a Flexible Benefit Plan fit into your salary?
A Flexible Benefit Plan (FBP) is a salary-structuring arrangement, which allows you to choose how certain predefined portions of your compensation are allocated, within the limits set by your employer. These adjustments may include telephone expenses, meal benefits, Leave Travel Allowance (LTA) or an employer contribution to NPS. But remember this, your total compensation remains unchanged.
For illustration, suppose your salary structure includes ₹24,000 that can either remain within a regular taxable salary component or be allocated towards a benefit offered under your employer’s FBP. If telephone expenses are one of the available options and you choose that benefit, the same ₹24,000 is assigned to the telephone component according to the employer’s policy.
If the benefit qualifies for favourable treatment under the applicable provisions and you meet the prescribed conditions, the amount included in your taxable salary may be lower. If those conditions aren’t met, the benefit can remain taxable.
Where does the tax saving in flexible benefit plan actually come from?
Let’s continue with the ₹24,000 already included in your salary structure. When paid as a regular salary, the ₹24,000 is generally included in your taxable income. Under an FBP, your employer can structure this ₹24,000 as a benefit instead of regular salary. The tax treatment of that benefit then determines how much, if any, is included in your taxable income.
If this ₹24,000 is allocated as LTA and you incur ₹15,000 in eligible travel expenses, ₹15,000 can qualify for the LTA exemption, subject to the applicable conditions. Your taxable income is therefore lower by ₹15,000, while the remaining ₹9,000 is taxable. If you are in the 30% tax bracket, the ₹15,000 exemption could reduce your tax by ₹4,500, before cess and other applicable provisions.
The tax saving, therefore, comes from the amount of the ₹24,000 that qualifies for the exemption, and not from the ₹24,000 allocation itself. The Flexible Benefit Plan provides the structure for allocating part of your salary to the benefit; the applicable tax provision determines the resulting tax benefit.
What components can be included in an FBP?
The components available under a Flexible Benefit Plan depend on your employer’s compensation policy. There is no standard statutory list that every employer must follow.
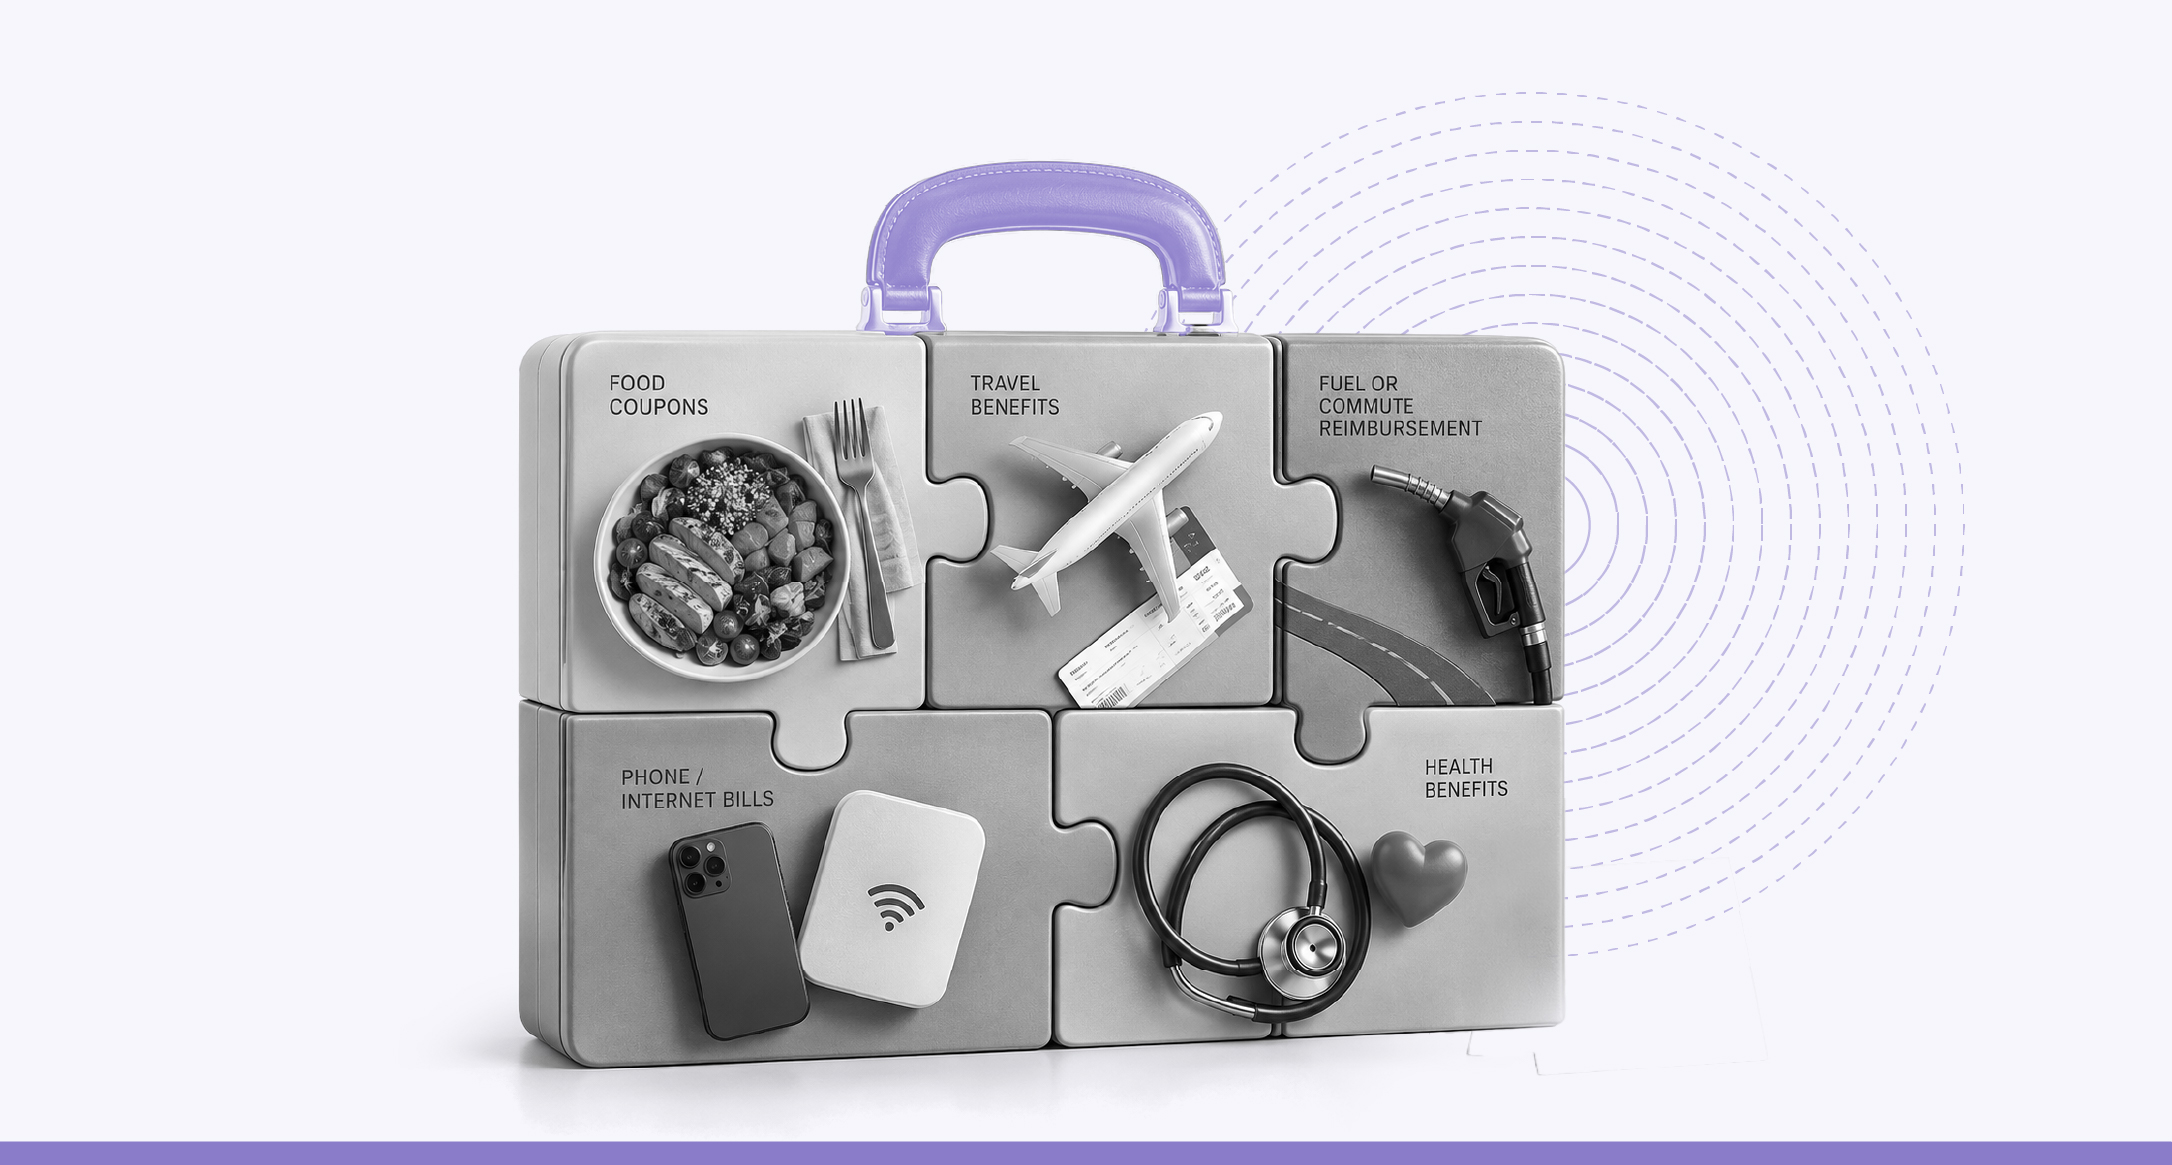
Common FBP components may include Leave Travel Allowance (LTA), telephone or mobile benefits, meal benefits, gift Vouchers, employer contributions to the National Pension System (NPS), gifts or vouchers, and certain other allowances or perquisites. Each component is taxed according to the provision that applies to that particular benefit.
Being included in an FBP doesn’t make a benefit tax-free. The tax treatment still depends on the relevant provision, the way the benefit is provided and any conditions attached to it.
Can FBP components reduce your taxable salary?
Some FBP components can reduce the amount of salary that ultimately becomes taxable, provided the applicable tax rules give that benefit an exemption, deduction or concessional valuation.
Suppose a part of your compensation would otherwise be paid as regular taxable salary. Your employer may allow you to allocate that amount towards an FBP component instead. The allocation alone doesn’t reduce your taxable income. You then have to apply the tax rules governing that particular benefit.
Consider an allocation of ₹24,000 towards a benefit. You cannot assume that the entire ₹24,000 will disappear from your taxable salary simply because it sits within the FBP. If only ₹15,000 qualifies for the exemption, your taxable income falls by ₹15,000 and the remaining ₹9,000 continues to be taxable.
The same approach should be used for every FBP component. Identify the benefit your employer offers, check the tax provision that applies to it, and determine how much of the amount is exempt, deductible, or taxable under the prescribed rules.
FBP changes the way part of your compensation is delivered. The tax provision attached to the chosen benefit decides whether that restructuring actually lowers your taxable income.
An FBP can make your salary structure more flexible, but its value depends on how carefully you choose the available components. Therefore, you can sit with a Qualified Financial Advisor (QFA) to review your current salary structure and if you can restructure it to your benefit, especially for tax planning. Here, the useful question isn’t how much of your salary you can move into the plan, but whether the benefits you select fit your actual expenses and qualify for the intended tax treatment.